Define the universe
Region, asset class and index family come first. A Taiwan-equity ETF and a US total-market ETF sit on different pages in our articles precisely because their comparison would flatter the screen.
Exchange-traded funds arrive by the dozen with every index revision — same-sounding wrappers, different expense structures, different index rules, different fine print. Our free editorial articles show how AI methods such as document parsing, factor screening and peer clustering sort that pile into comparisons you can actually read.
Everything here is published to be checked, not trusted: the criteria behind every screen are stated alongside it, and questions about our method are welcome at any time.
One narrow brief, followed honestly: how artificial intelligence is used — and where it misleads — when exchange-traded funds are screened and compared.
Every piece works from public fund documents — prospectuses, factsheets, holdings files, exchange disclosures — and shows the mechanics of the screen instead of asserting its verdicts. Nothing is recommended, and nothing is sold.
Before two exchange-traded funds can be called comparable, five pages of questions have to pass in working order.
Region, asset class and index family come first. A Taiwan-equity ETF and a US total-market ETF sit on different pages in our articles precisely because their comparison would flatter the screen.
Total expense ratio, swap fees for synthetic structures where they apply, and the spread paid at the door — matched against the index each fund actually tracks, stated side by side.
Tracking difference shows what an index returned minus what the fund delivered; tracking error shows how wildly it moved while doing so. Both figures appear in every comparison the articles build.
Assets under management, traded value and bid-ask spread decide whether a screen survivor can be bought or sold at a fair price — a fund that trades by appointment fails on trading, not on theory.
Text-mining routines sweep prospectuses for securities-lending terms, dividend handling and index-reconstruction rules that a ratio table hides. Our editors then translate what the parse found — and what it missed.
Editorial work serves readers best when its edges are visible.
Reads well if
You build your own shortlists, you want to see the mechanics of a screen before trusting it — the index rules, the cost arithmetic, the clustering methods — and you enjoy questioning them.
Not built for
Every page here describes methods in general terms: nothing interprets one reader's finances, recommends a fund, or places a trade. This is an editorial publication, not licensed financial advice.
How inquiries run
Read something you want clarified — an unexplained term, a comparison criterion, a step in the screening process? Send it in through the contact form and the answer comes back by email from the same address on Xinyi Road.
The research is written in the Xinyi District of Taipei City — the district whose skyline anchors the last band below — and answers inquiries from there in writing.
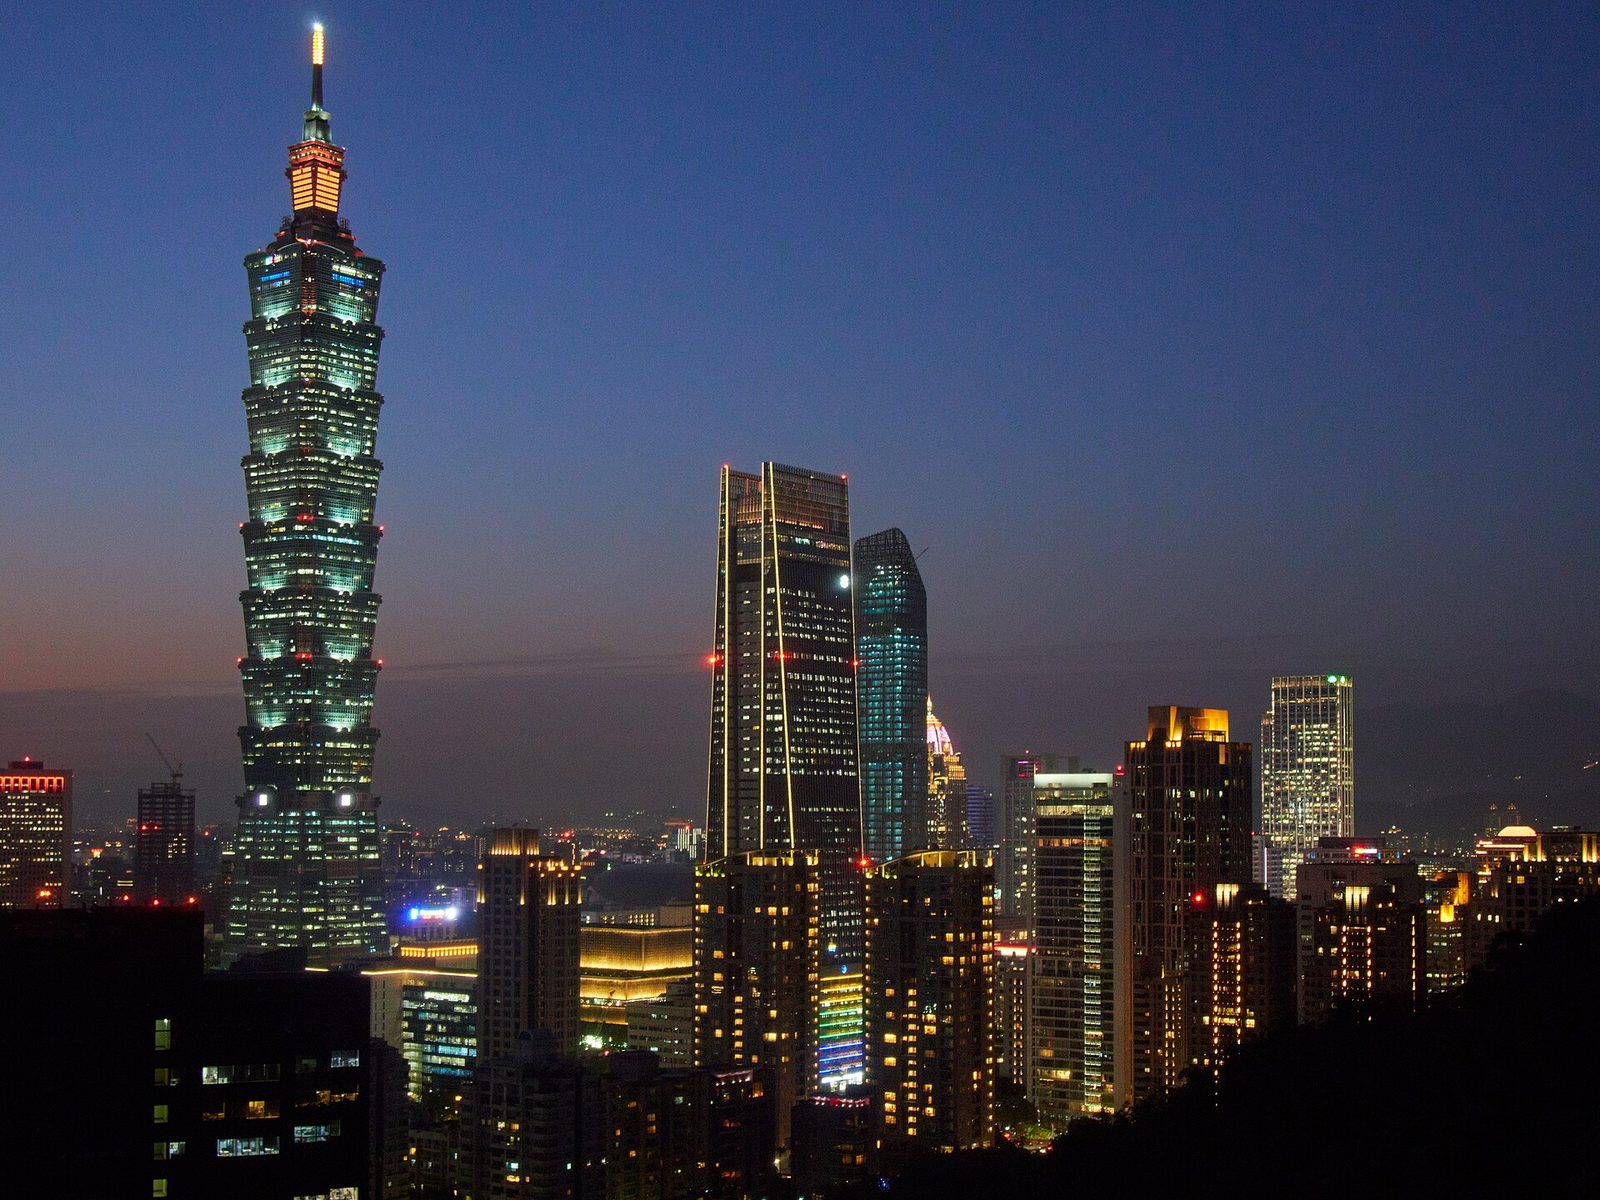
Taipei 101 over the Xinyi District at night — the district our registered address sits in. Photo: lumoplank, CC0, via Wikimedia Commons.
The same four questions arrive with nearly every inquiry. Here they are with the short answers.
No. The articles are journalistic descriptions of how AI-assisted exchange-traded-fund screening works in general terms. Nothing on the site interprets your finances, recommends a fund, or sizes a position.
Also no. Checkout buttons, subscription tiers and paid plans do not exist on this site. The articles are free to read, and asking about a published one costs nothing.
In document parsing and similarity work: language models read fund filings, statistical routines cluster similar ETFs, and screen pipelines test each fund against the index it claims to track. The articles explain each stage with examples drawn from public disclosures.
Yes — that is what the inquiry form is for. Requests to clarify a comparison criterion, define a term, or revisit a screening step all belong there, and replies arrive by email.